Some links on this page are affiliate links. If you buy through them, we may earn a commission at no extra cost to you, and it never affects our recommendations. See our affiliate disclosure.
How do you get insurance to pay for a night guard? You make the medical case before the dentist makes the guard, and you do it in order. First, a dental exam documents active grinding damage. Then the billing office files a predetermination with the right code. Then the dentist makes and bills the guard. If the plan denies the claim, you appeal with a letter of medical necessity. Most people skip the predetermination, and that skip causes the surprise bill weeks later. This page walks the sequence step by step, names the billing codes, explains what a denial means, and covers your options when a plan excludes bruxism appliances.
Wondering whether your plan covers night guards at all? Start there. This guide assumes coverage is at least possible, and it focuses on getting an eligible guard approved and paid.
Key Takeaways
- To get a night guard covered by insurance, work the steps in order. The move that changes the outcome is a predetermination with code D9944, filed before the dentist fabricates the guard, so the plan commits a number in writing.
- A night guard clears the “medically necessary” bar only when your chart shows grinding damage. A billing code with no clinical narrative draws the most common auto-denial.
- A licensed dentist must make and bill the guard. Plans almost never reimburse an over-the-counter or mail-order guard.
- A denied claim usually comes down to one of four reasons, and your Explanation of Benefits names which one.
- Appeal an internal denial in writing. Attach a letter of medical necessity and photos of the tooth wear.
- Standalone dental plans usually fall outside the federal appeal rules that cover medical insurance. Your reliable external step is a complaint to your state insurance department.
Get a Night Guard Covered by Insurance: the Short Version
Here is how to get a night guard covered by insurance, start to finish. First, see a dentist for an exam that records tooth wear or jaw symptoms in your chart. Second, ask the billing office to file a predetermination under the occlusal guard code. The plan then returns a percentage and your estimated share in writing. Third, have the dentist make and bill the guard. Fourth, read the Explanation of Benefits once the plan processes the claim. Fifth, appeal with a letter of medical necessity if the plan says no.
Where a plan covers an occlusal guard, it usually pays about 50% of the allowed amount after the deductible. It also limits you to one guard every one to five years, and the benefit eats into your annual maximum. A new plan may add a waiting period first. Once you know your percentage, night guard cost with insurance shows how the dollars work out.
Step 1: Get the Diagnosis Documented
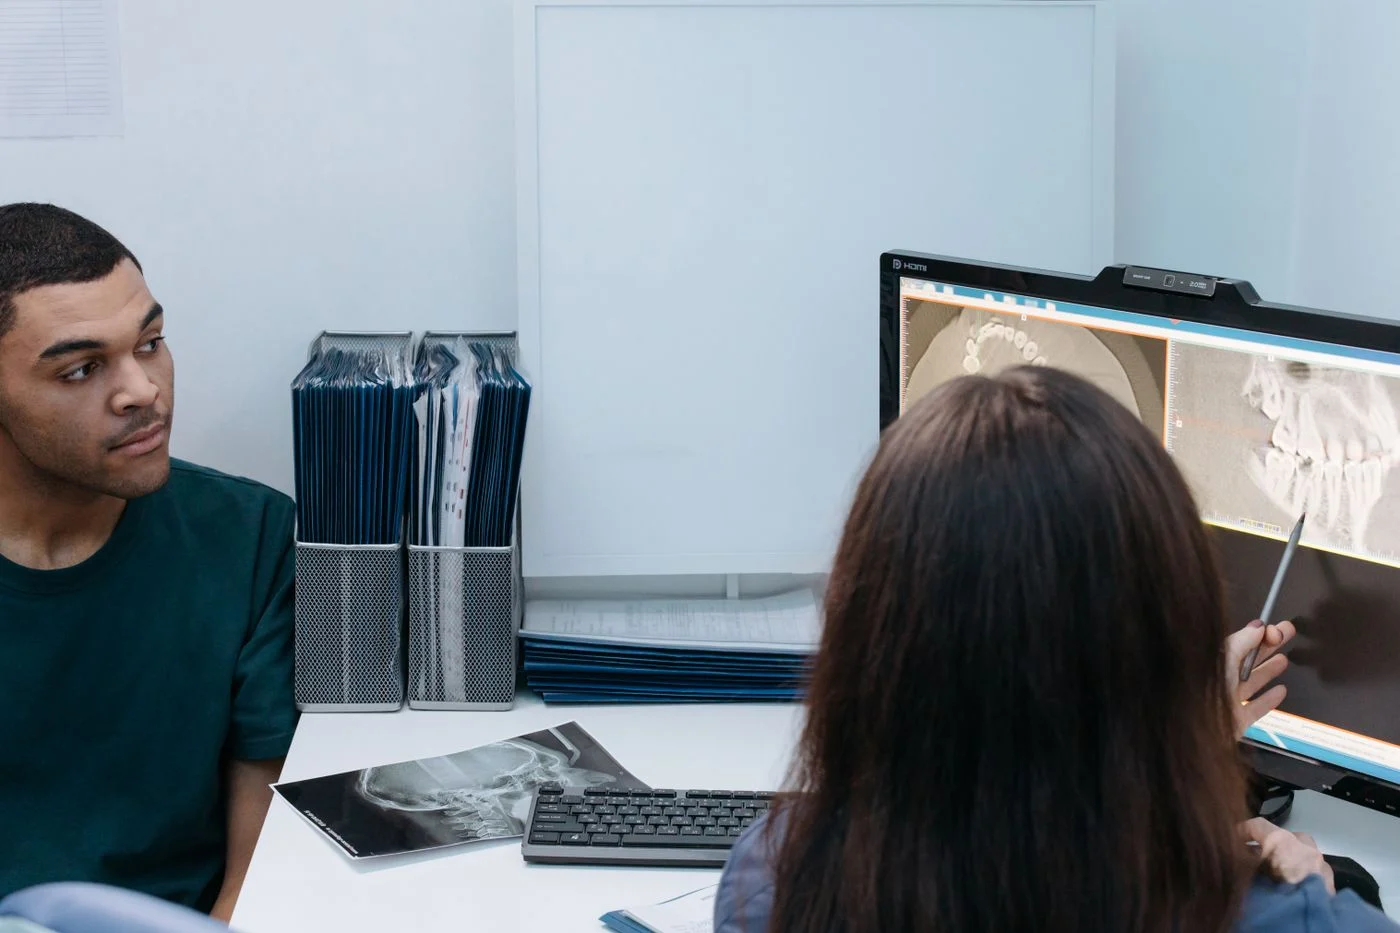
Insurance treats a night guard as medically necessary when your record shows a problem it prevents. Your dentist charts the active wear, such as flattened cusps, worn enamel, cracked teeth, or fractured fillings. Your dentist also notes a diagnosis of bruxism or clenching. Payers want three things, according to eAssist Dental Solutions: a panoramic x-ray, photos of the damaged or ground-down teeth, and a clinical narrative that names the arch and affected teeth. As one dental practice puts it, insurance is more likely to help “if there’s documented tooth wear” and “you have jaw pain or TMJ symptoms,” per Merion Village Dental.
Most guard claims that fail on the first pass fail for one reason: a billing code with a thin or missing narrative. So ask your dentist to record the findings at the visit where the guard comes up, and to keep the intraoral photos. If jaw pain is your main issue rather than tooth wear, the claim may belong to your medical plan instead. The four coverage buckets guide explains that split.
Step 2: File a Predetermination With the Right Code
Predetermination versus preauthorization
The American Dental Association calls these “distinct and different terms and processes” that “are not interchangeable.” It also warns that a predetermination does not lock in payment: “the estimated payments for services are not guaranteed,” per the ADA guidance on pre-authorizations. A predetermination estimates what your plan will pay for a proposed treatment. That estimate reflects your eligibility and remaining benefits on the day the plan reviews it. A preauthorization, where a plan offers one, can come closer to binding. Offices use both words loosely, so ask which one they plan to submit.
The occlusal guard codes
Dentists bill a custom night guard under one of three current codes. D9944 covers a hard, full-arch guard. D9945 covers a soft, full-arch guard. D9946 covers a hard, partial-arch guard. The ADA retired the older single code, D9940, effective January 1, 2019, and split it into these three, per the 2019 code-change notice from New York State Medicaid. A claim that still uses D9940 bounces, so confirm the office has the current code. Plans also disagree on how to classify the code, some as basic and some as major, which is why the percentage shifts from one plan to the next.
What the predetermination returns
The predetermination comes back with three numbers in writing before the lab fee starts: the coverage percentage, the plan’s allowed amount for the code, and your estimated share. The front desk cannot promise that number when it says the guard will be free. That is why a bill for a few hundred dollars turns up a month later. The predetermination costs nothing to request and takes a week or two.
Step 3: Make Sure It Is Billed Correctly
Three billing details decide whether an eligible claim pays cleanly. First, the dentist makes and bills the guard, rather than reimbursing you for a device you bought elsewhere. Second, the claim goes to an in-network dentist where possible. Out of network, the plan pays its percentage of a lower allowed amount and you owe the balance. Third, the claim uses the current code, with the predetermination already on file. Over-the-counter and mail-order guards sit outside all of this. As GoodRx notes, dental insurance “typically” covers a night guard only when “your dentist determines” it is medically necessary. A guard you ordered without a dentist does not qualify.
If Your Night Guard Claim Is Denied
Read the denial
Match the wording on your Explanation of Benefits to one of four standard reasons. One, the plan excludes bruxism appliances outright. Here the exclusions list matters more than the benefits summary. Two, the file held no documentation of active grinding damage. Three, you already used a covered guard inside the frequency window. Billing references put that window at anywhere from one guard per 36 months to one per arch every seven years. Four, the claim used the retired code D9940. The reason tells you which appeal, if any, is worth your time.
File an internal appeal
Send a written appeal to the plan’s appeals unit, with a letter of medical necessity from your dentist. A usable letter names three things, which billing specialists call the parts a payer narrative needs: the diagnosis, the clinical findings with dates, and the treatment objective. Attach annotated photos of the wear facets and a short timeline of symptoms. On an employer plan governed by federal benefits law, the insurer generally must answer a non-urgent appeal within about 60 days, per the U.S. Department of Labor.
Escalate if the internal appeal fails
Ask whether the office can request a peer-to-peer review, where your dentist speaks directly to the plan’s dental consultant. If the denial holds, file a complaint with your state insurance department. If you decide to buy a guard yourself instead, the best night guard for teeth grinding guide compares the options. The National Association of Insurance Commissioners explains that every state runs a commissioner’s office that regulates carriers and looks into unfair denials. One dental-billing resource suggests you attach the original claim and denial letter, your internal appeal correspondence, the patient records and X-rays, and a written statement on why the denial is unfair, per Veritas Dental Resources. Standalone dental plans usually fall outside the federal external-review process that covers major medical plans. So for those plans, the state complaint is your main external lever.
Does the Carrier Matter?
The medically necessary bar and the billing codes hold steady across carriers. The classification, the percentage, and the frequency limit are the parts that shift by plan. If you have Delta, does Delta Dental cover night guards breaks it down by product, because Delta is dozens of member companies rather than one. Guardian and MetLife guides are in progress.
If Your Appeal Fails or the Plan Excludes Night Guards
If the plan excludes bruxism appliances, or the after-insurance price lands close to retail anyway, an online custom guard is the practical fallback, and our custom night guard vs boil-and-bite guide weighs it against the drugstore and dentist routes. It runs about $95 to $235, with no claim, no frequency limit, and no medical-necessity test. Sentinel Mouthguards prices its guards from $165 to $235. Chomper Labs runs about $119 to $179, and ClearClub and SportingSmiles both start near $95. A dental discount plan is another route: 1Dental and similar plans knock 20% to 50% off the occlusal guard code, with no claim to file and no documentation. Either way, a night guard treats bruxism, so HSA and FSA money works for it. For the route-by-route cost, see how much a night guard costs. For whether the dentist guard earns its premium, see the night guards guide.
Frequently Asked Questions
How do I get my insurance to pay for a night guard?
Get a night guard covered by insurance in this order. Have your dentist document the grinding damage in your chart. Ask the billing office to file a predetermination with code D9944 before the dentist makes the guard. Use a dentist-billed appliance. Appeal with a letter of medical necessity if the plan denies the claim. The predetermination is the step that heads off a surprise bill.
Do I need a predetermination for a night guard?
No rule requires one, but it is the single best move. It makes the plan commit a percentage and an allowed amount in writing before the lab fee starts. Keep in mind that a predetermination only estimates the payment, and it still depends on your eligibility on the date of service.
Why was my night guard claim denied?
Usually one of four reasons: the plan excludes bruxism appliances, the file showed no documentation of active grinding damage, you used a covered guard inside the frequency window, or the claim used the retired code D9940. Your Explanation of Benefits names the reason.
What is a letter of medical necessity for a night guard?
It is a written statement from your dentist. It names the diagnosis, the tooth wear or fractures with dates, the harm if the grinding continues, and the specific appliance and code requested. A medical-plan route for TMJ or sleep apnea sometimes needs a physician’s signature too.
Can I appeal if my dental insurance denies a night guard?
Yes. File an internal appeal in writing, with the letter of medical necessity and photos of the tooth wear. If that fails and you have a standalone dental plan, file a complaint with your state insurance department, because those plans usually fall outside the federal external-review process.
Will insurance reimburse a night guard I bought online?
Rarely. Most plans only pay for a custom guard that a licensed dentist makes and bills. An online custom guard is a cash purchase, though HSA or FSA money covers it.
The Bottom Line
To get a night guard covered by insurance, work in order. Start with a documented diagnosis. Add a predetermination with code D9944. Have the dentist bill the guard. Appeal with a letter of medical necessity if the plan says no. Where a plan covers a guard, expect about 50% after the deductible, once every few years. If the internal appeal fails, your state insurance department is the next step, not a federal review. And if the plan excludes bruxism appliances, an online custom guard at $95 to $235 with HSA or FSA money is the cleaner option. For the coverage rules behind all of this, see does dental insurance cover night guards and the main night guards guide.